
Motorcycle insurance doesn’t have to drain your wallet. We at Leslie Kay’s, Inc. know that finding cheap motorcycle insurance options takes strategy, not luck.
This guide walks you through proven ways to cut your premiums, compare carriers effectively, and avoid costly mistakes that most riders make.
Three Proven Ways to Cut Your Motorcycle Insurance Costs
Complete a Motorcycle Safety Course
Safety courses prove to insurers that you’re a lower-risk rider. Most major carriers offer discounts ranging from 5% to 15% when you complete an approved motorcycle safety course, according to data from the National Highway Traffic Safety Administration. The Motorcycle Safety Foundation’s Basic RiderCourse costs between $100 and $350 in most states, but that investment pays for itself within the first year on most policies. Insurance companies recognize that riders who take these courses file fewer claims, making them genuinely cheaper to insure.
Raise Your Deductible
Your deductible is one of the most powerful levers you control. Raising your deductible from $500 to $1,000 typically cuts your comprehensive and collision premiums by 10% to 25%, depending on your carrier and location. The math works in your favor if you’re willing to self-insure smaller incidents-most motorcycle repairs under $1,000 involve minor damage like scratches or small dents. The Insurance Information Institute reports that riders who increase their deductibles save an average of $200 to $400 annually. This strategy only makes sense if you have an emergency fund to cover that higher amount without financial strain.
Bundle Your Policies for Multi-Vehicle Discounts
If you’re already paying for auto or home insurance, consolidating your motorcycle policy with those same carrier often produces multi-policy discounts of 15% to 25%. Riders who consolidate their coverage with one insurer pay significantly less than those splitting policies across multiple companies. The convenience of one billing statement and one customer service relationship makes administration simpler too, which carriers reward with better rates.
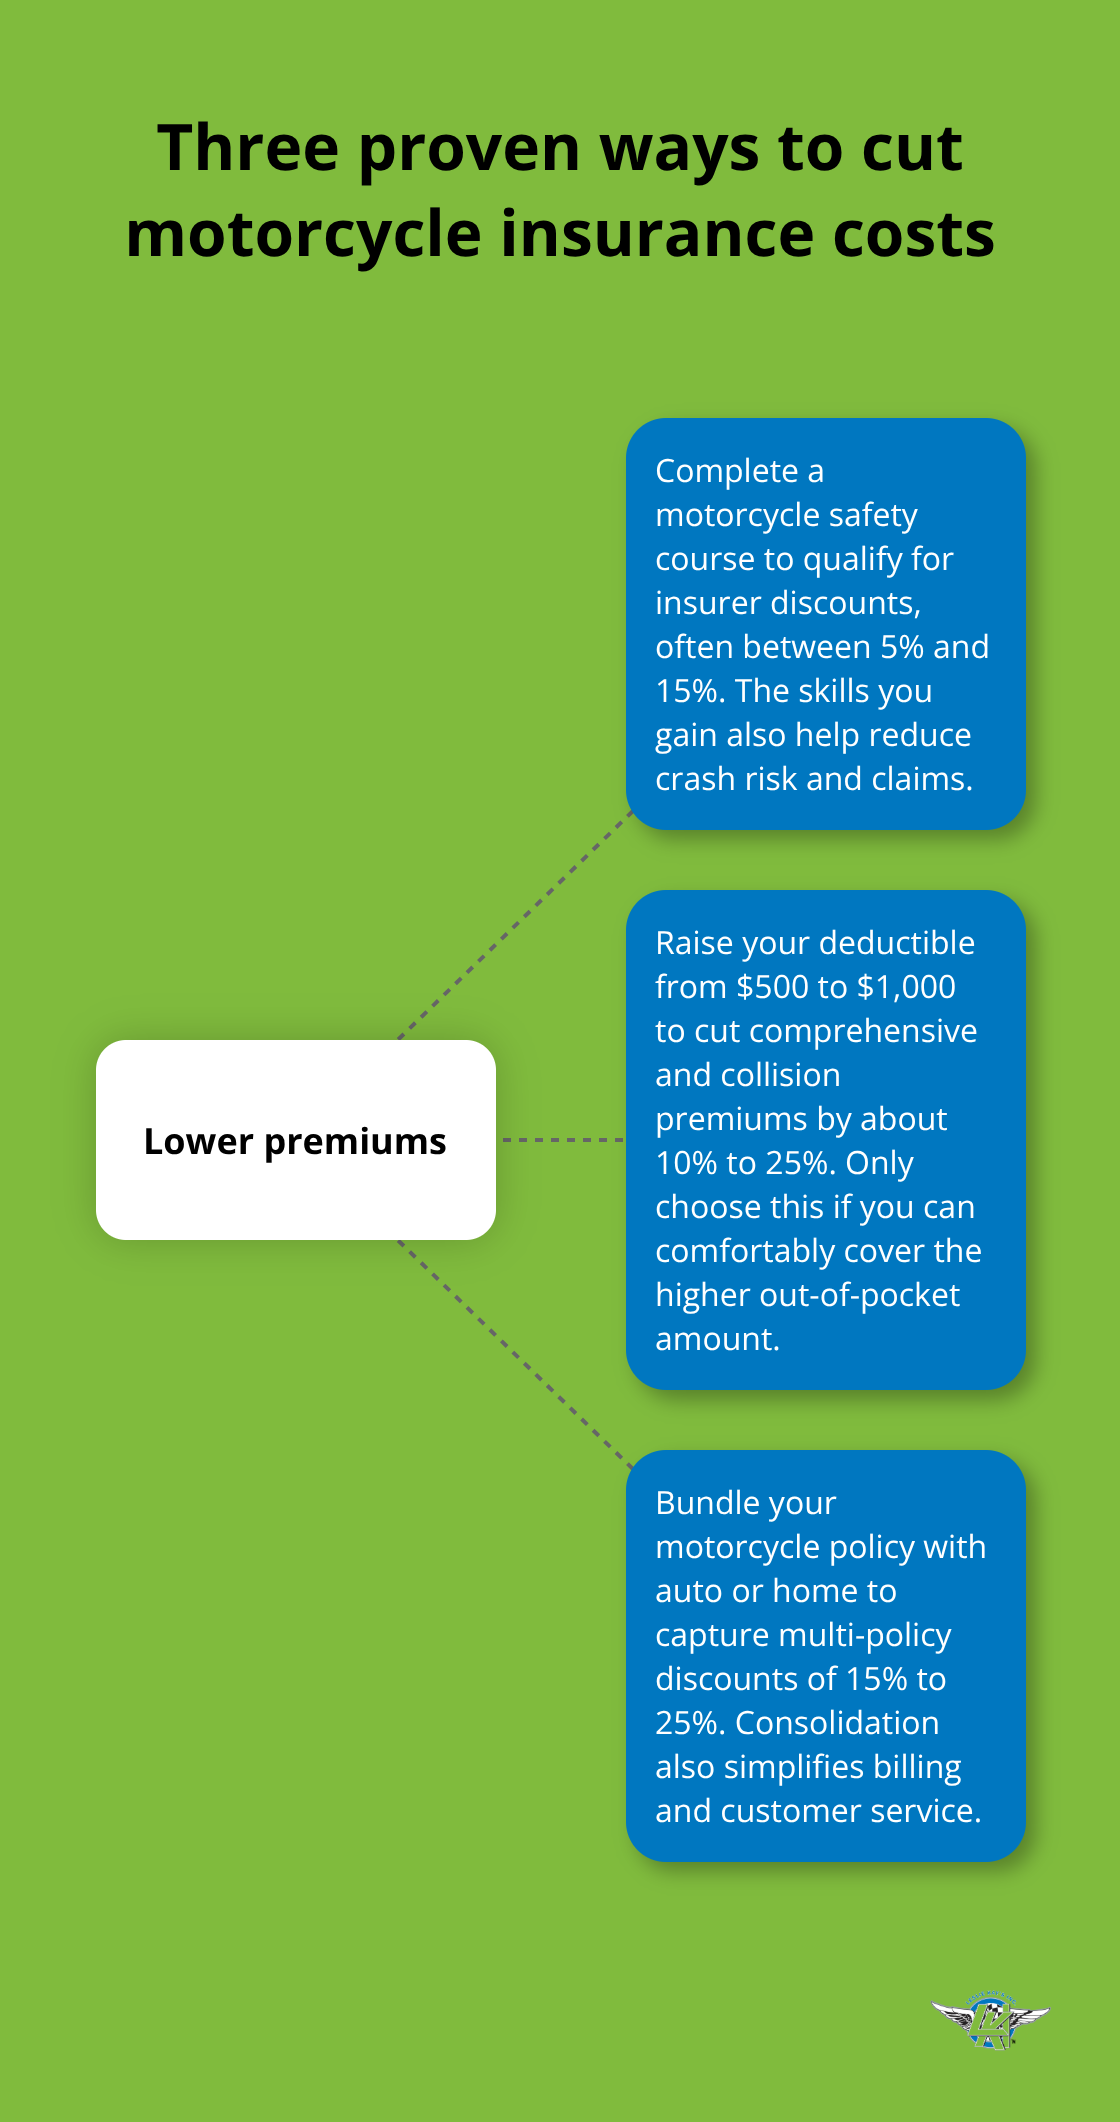
These three strategies form your foundation for lower premiums. The next step involves comparing what different carriers actually offer-because the best discount means nothing if you’re comparing it against inflated base rates.
Shop Multiple Carriers to Find Your Real Best Rate
Why Comparing Quotes Matters for Your Wallet
Most riders request quotes from two or three insurers and stop there. That approach costs you money. Premiums for identical coverage vary significantly across different carriers for the same rider profile. Shopping at least five to seven insurers gives you a realistic picture of what your actual costs should be. Some carriers price aggressively for riders with clean records and safety training, while others focus on high-risk profiles. You won’t know where you stand without comparing multiple options.
Prepare Your Information Before You Call
Start by gathering your riding history, vehicle details, and current coverage information before contacting insurers. Have your motorcycle’s VIN, engine size, year, make, and model ready. Document any safety modifications, anti-theft devices, or riding courses you’ve completed.
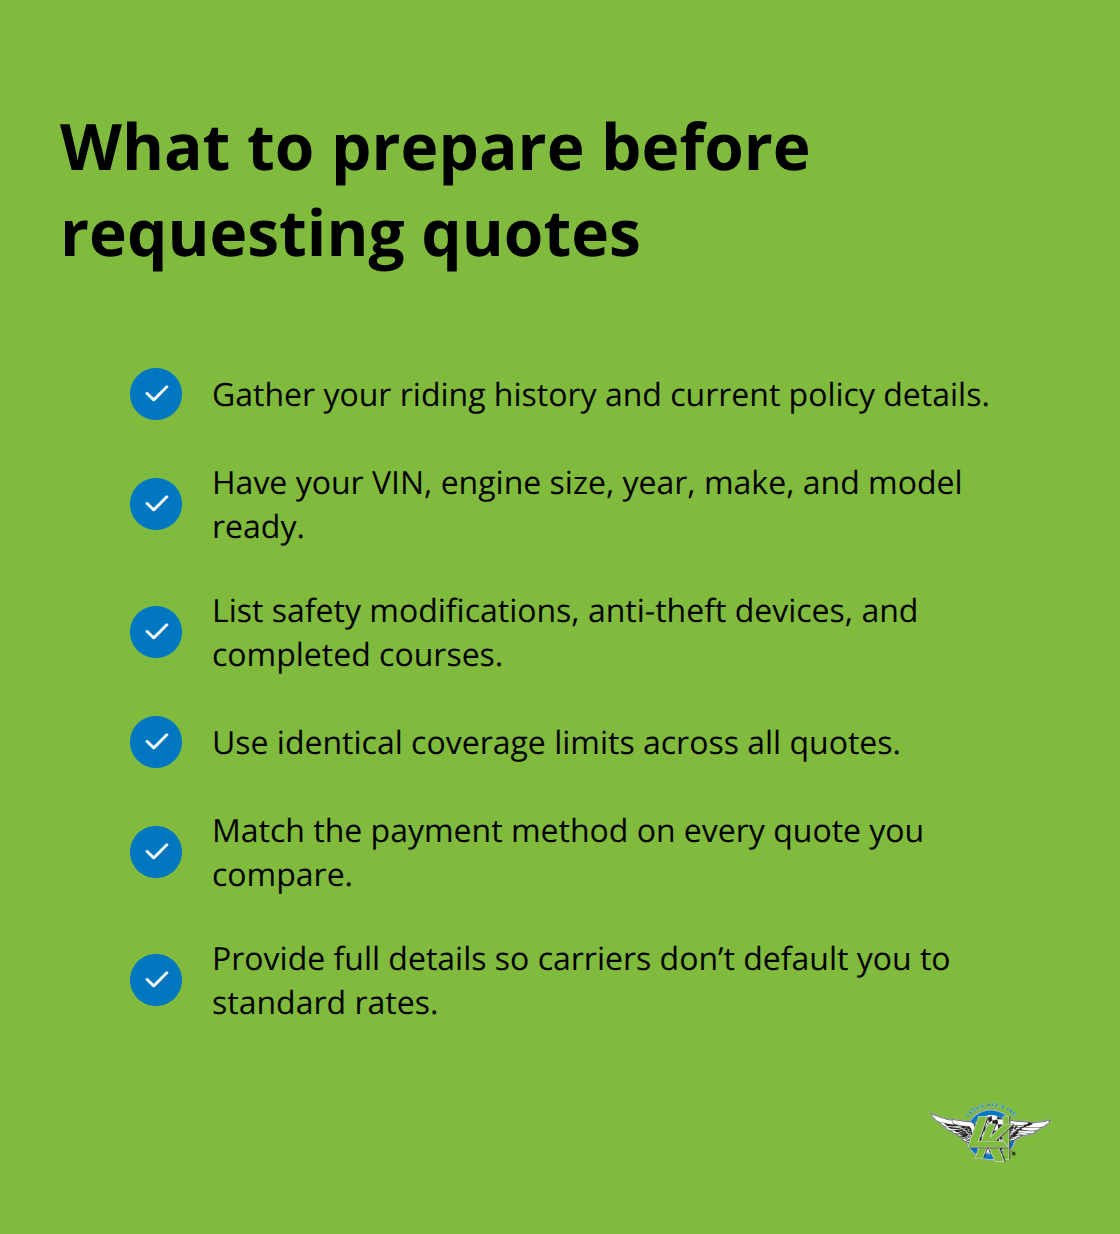
Carriers weight these factors differently, and missing details forces them to quote you at standard rates rather than your actual risk profile. When you call or request quotes online, use identical coverage limits across all quotes so the numbers truly compare apples to apples. A quote with lower liability limits might look cheaper but won’t protect you adequately.
Spot Red Flags in Your Quotes
Watch for quotes that seem suspiciously low compared to others. If five insurers quote you around $600 annually and one quotes $350, that outlier likely carries hidden restrictions, higher deductibles you didn’t notice, or coverage gaps. Read the fine print on each quote before celebrating a bargain. Some carriers exclude certain types of riding, limit coverage for riders under 25, or impose waiting periods for claims. Others offer significantly better rates if you pay in full rather than monthly, which affects your true annual cost. Request quotes with the exact same payment method to eliminate this variable.
Factor in Bundling and Service Quality
Track which carriers offer bundling discounts for your auto or home policies, as consolidation often saves money compared to motorcycle-only quotes. Compare customer service ratings through the National Association of Insurance Commissioners complaint database, not just online reviews, since claims support matters far more than pre-purchase politeness when your bike needs repairs. An independent agency can quote many different insurance carriers at once on your behalf and present side-by-side options tailored to your actual needs.
Once you’ve narrowed your options based on price and service quality, the next challenge emerges: avoiding the mistakes that cause premiums to spike after you’ve already purchased your policy.
Mistakes That Quietly Spike Your Motorcycle Insurance Rates
Underestimating Your Liability Coverage Needs
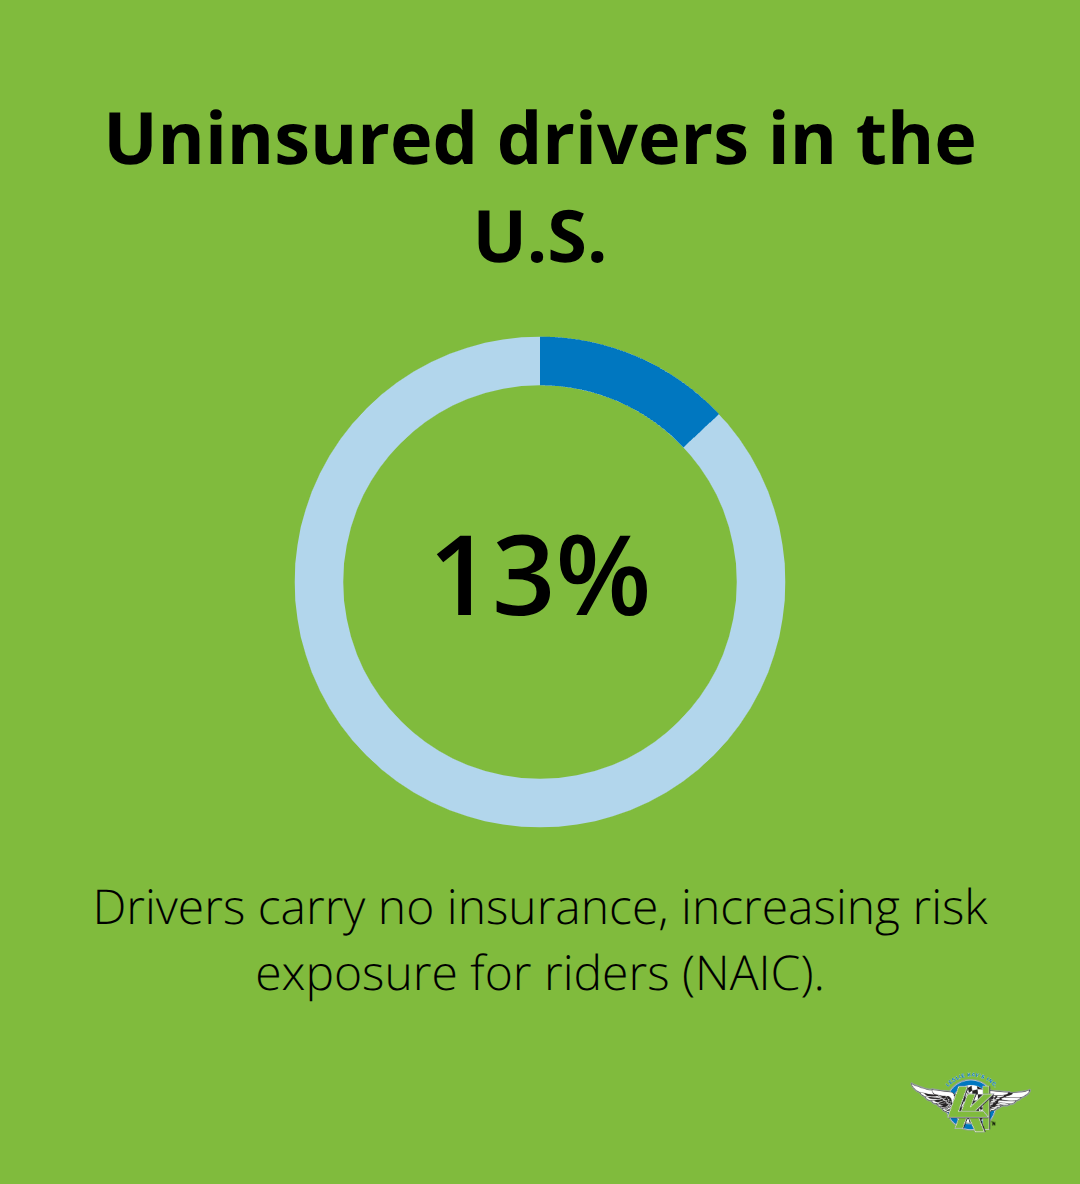
Most riders purchase bare-minimum liability coverage because it feels cheaper upfront. Many states legally require only 25/50/25 liability limits, meaning $25,000 bodily injury per person, $50,000 per accident, and $25,000 property damage. That coverage evaporates instantly in a serious accident. A single collision where you injure another rider and damage their bike can easily exceed $100,000 in claims. Underinsured riders face personal lawsuits that demolish your finances far longer than higher premiums would have cost. Try minimum liability limits of at least 100/300/100 to actually protect your assets, and uninsured motorist coverage of 100/300 since roughly 13% of drivers carry no insurance according to the National Association of Insurance Commissioners.
Failing to Report Safety Features and Modifications
The second costly mistake involves failing to disclose safety modifications and anti-theft devices when you purchase your policy. Riders install GPS trackers, alarm systems, or engine guards but never mention these upgrades to their insurer. When a claim happens, insurers discover undisclosed modifications during investigation and deny coverage or cancel your policy entirely. Conversely, many safety features qualify for discounts ranging from 5% to 15% depending on your carrier. Anti-lock braking systems, factory alarm systems, and daytime running lights reduce your risk profile and your premium. Report every modification and safety device to your insurer-these additions protect both your bike and your wallet.
Ignoring Annual Policy Reviews
The third mistake compounds these problems: you ignore your policy annually. Your situation changes every year (your bike depreciates, your riding record improves, new discounts become available, or competing carriers launch better rates). Riders who review their policies only when renewing often pay 20% to 40% more than riders who shop annually. Contact your agent or request new quotes each year, especially if you’ve completed additional safety training, installed security features, or reduced your annual mileage. These changes directly lower what you should pay.
Final Thoughts
Finding affordable motorcycle insurance options requires action, not wishful thinking. The strategies we’ve covered-completing a safety course, raising your deductible, and bundling policies-form your foundation for lower premiums. Shopping multiple carriers separates riders who overpay from those who actually get competitive rates. Most importantly, avoiding the three costly mistakes (underestimating coverage, hiding modifications, and skipping annual reviews) protects both your bike and your finances long-term.
Start your search today by gathering your motorcycle details and riding history, then request quotes from at least five carriers using identical coverage limits. Track which insurers offer bundling discounts for your auto or home policies, since consolidation frequently saves 15% to 25% annually. Complete a safety course if you haven’t already-that 5% to 15% discount pays for itself within months on most policies.
An independent agency can handle the heavy lifting by shopping multiple carriers simultaneously and presenting side-by-side options tailored to your actual needs. Leslie Kay’s specializes in motorcycle coverage across multiple states and offers seven-day-a-week service when you need support. The difference between overpaying and getting genuine cheap motorcycle insurance options often comes down to one decision: will you spend an hour comparing quotes, or will you accept whatever your first insurer quotes?
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.