
Class B Motorhome Insurance
Protection that keeps you riding with confidence.
Class B Motorhome Insurance
Protection that keeps you riding with confidence.
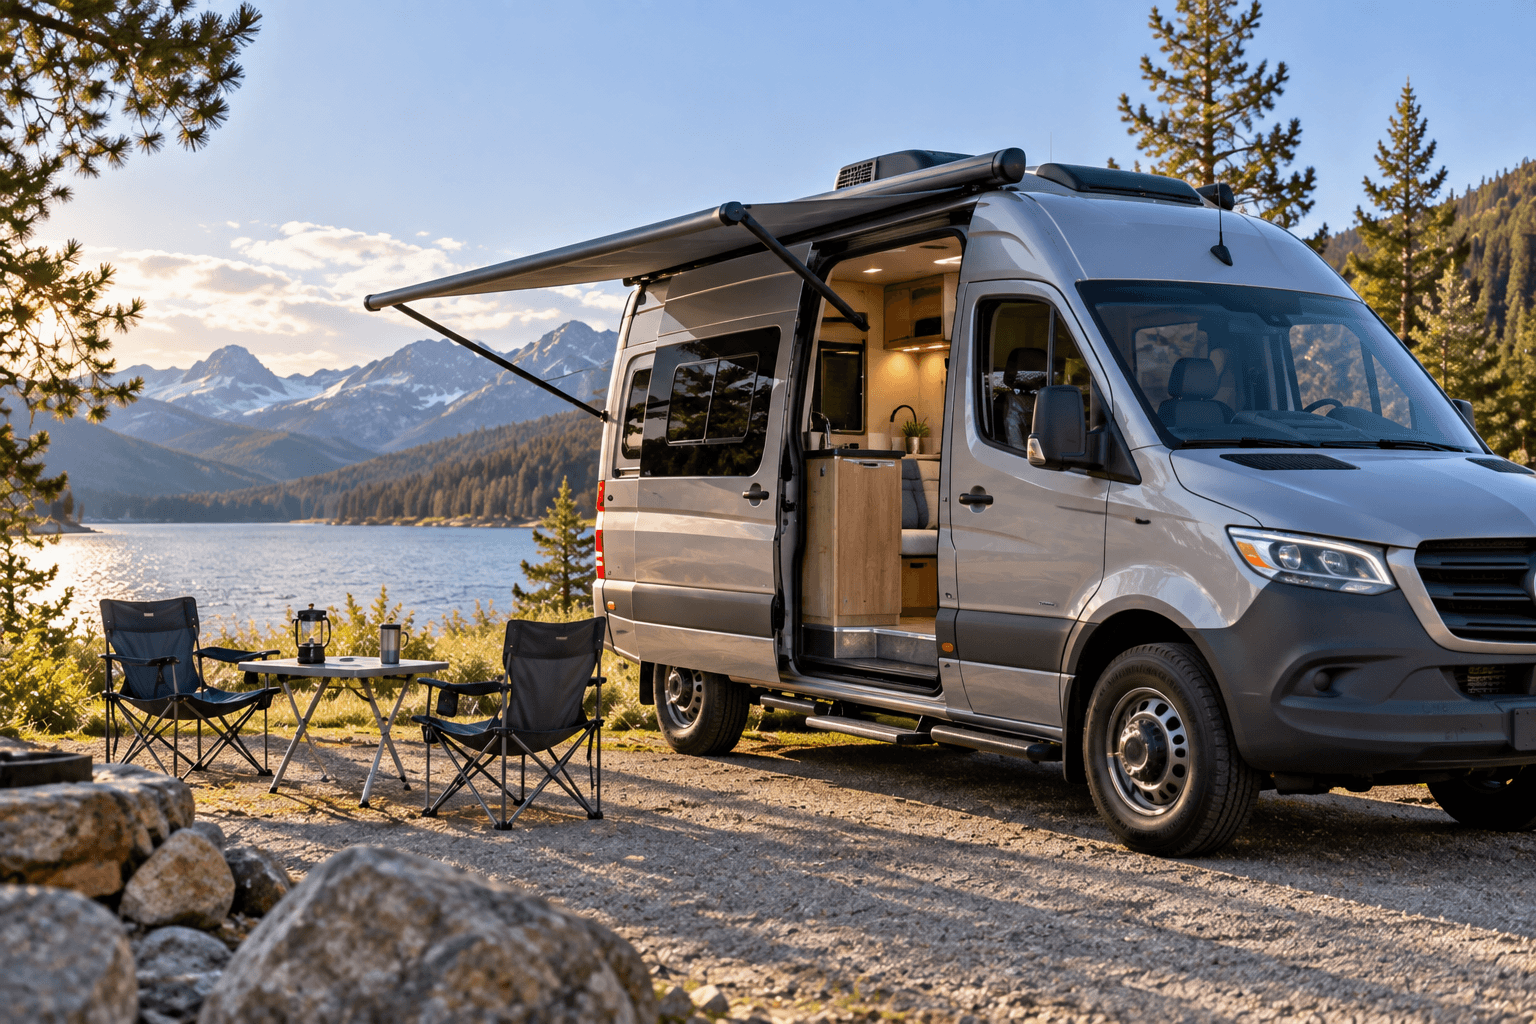
Leslie Kay’s Inc. Can Insure Your Class B Motorhome
We Can Insure Your Ride
Class B motorhomes, often called camper vans, package sleeping, cooking, electrical, plumbing, and storage systems into a van-sized vehicle. They may look like ordinary vans, but their conversion equipment and travel use create additional insurance considerations. A policy designed around the actual vehicle or watercraft may help protect the owner from covered financial losses that an auto, homeowners, or basic recreational policy might not address.
Leslie Kay’s, Inc. can help owners in Florida compare class b motorhome insurance options from multiple insurance companies. The goal is to match how the unit is owned, operated, equipped, transported, and stored with an insurer whose rules and policy form fit those facts.
Contact Us
Speak to a specialized insurance
professional 7 days a week
Why Specialized Class B Motorhome Insurance Matters
Motorhome ownership combines a vehicle exposure with many of the property and liability concerns associated with a temporary residence. A lender, marina, campground, association, or trail system might also require proof of coverage or minimum liability limits. Even when insurance is optional, repair, replacement, medical, legal, towing, and cleanup expenses can be substantial.
The insurer should know whether the van was factory-built, professionally converted, or owner-built. Solar panels, lithium batteries, pop-tops, auxiliary heaters, cabinetry, and removable equipment may not be valued correctly if the vehicle is insured only as a standard van. No policy covers every loss, and coverage names that sound similar may work differently between companies. Eligibility can also change with value, age, modifications, operators, territory, and use.
Coverage Options to Consider
A suitable policy may combine several coverages. Availability, limits, deductibles, exclusions, and settlement methods vary, so each quote should be compared on more than price.
Liability Coverage
Liability coverage may respond when an insured is legally responsible for bodily injury or property damage arising from operation or use of the motorhome. Limits should be reviewed with the vehicle size, passenger use, travel patterns, and umbrella requirements in mind.
Collision and Comprehensive Coverage
Collision may help repair covered damage from an impact or rollover. Comprehensive may address covered non-collision losses such as theft, fire, falling objects, wind, hail, vandalism, or contact with an animal, subject to deductibles and policy terms.
Uninsured and Underinsured Motorist Coverage
This coverage may help when another driver causes an accident but has no insurance or insufficient limits. Availability and the exact protection provided vary by state and policy.
Roadside Assistance and Towing
A motorhome can require specialized towing and roadside equipment. Optional coverage may help with eligible towing, jump-starts, tire service, fuel delivery, or labor after a breakdown, but distance and reimbursement limits should be reviewed.
Personal Belongings and Attached Equipment
Motorhomes often carry electronics, camping equipment, clothing, tools, and permanently attached accessories. The policy should be reviewed for property limits, special sublimits, awnings, satellite equipment, solar components, and aftermarket upgrades.
Important Details to Review Before Choosing a Policy
Accurate information helps an insurer classify the risk and helps avoid surprises at claim time. For class b motorhome insurance, relevant details may include:
- Conversion type and documentation
- Stated vehicle value
- Daily-driving use
- Annual mileage
- Lithium battery and solar systems
- Pop-top or roof modifications
- Rental activity
- Storage and anti-theft measures
It is also helpful to discuss seasonal storage, winterization, campsite use, towing a small vehicle, and long trips away from home. If the unit is financed, rented to others, used for paid work, occupied full time, modified for higher performance, or taken outside the ordinary coverage territory, that fact should be raised before the policy begins.
How Value and Deductibles Affect a Claim
Covered losses may be settled using cash value, stated value, agreed value, replacement cost, or another method. Actual cash value reflects depreciation; agreed value may establish the covered value in advance, subject to the contract; and replacement-cost protection may have age, ownership, or replacement requirements.
Deductibles should be weighed against both premium and the owner’s ability to absorb a loss. Separate deductibles may apply to different coverages, and special deductibles or restrictions could apply to wind, named storms, theft, glass, or other causes. Photographs, purchase records, serial numbers, appraisals, and receipts for upgrades can make valuation easier.
Licensed in Florida and Multiple States
Leslie Kay’s, Inc. is an independent insurance agency licensed to serve clients in the following states:
- Alabama
- Arizona
- Arkansas
- California
- Colorado
- Connecticut
- Florida
- Georgia
- Illinois
- Indiana
- Iowa
- Kentucky
- Louisiana
- Maine
- Maryland
- Massachusetts
- Michigan
- Mississippi
- Missouri
- Montana
- Nebraska
- Nevada
- New Hampshire
- New Jersey
- New Mexico
Insurance availability, policy forms, carrier options, and requirements may vary by state. Contact the agency to discuss the location where the vehicle or watercraft is primarily kept and used.
Compare Class B Motorhome Insurance Options in Florida
An independent insurance agency can approach multiple carriers and explain meaningful differences in policy structure. A lower premium may come with a more restrictive valuation method, smaller accessory allowance, limited towing, narrower territory, or exclusions that matter for the way the unit is used.
Contact Leslie Kay’s, Inc. at 561-736-5400 to discuss class b motorhome insurance in Florida. Coverage is subject to underwriting, policy terms, conditions, exclusions, limits, and deductibles. An application and a conversation with a licensed insurance professional are needed to determine what may be available for a particular risk.
Class B Motorhome Insurance FAQs
Can a DIY camper-van conversion qualify for Class B coverage?
Possibly, but eligibility varies. Insurers may request photographs, receipts, inspection information, or proof that electrical and propane systems were installed safely.
Is a Class B covered when used as a daily driver?
Some policies allow regular transportation use, while others are priced for recreational use. The actual commuting and annual mileage should be disclosed.
Are solar panels and lithium batteries automatically covered?
Permanently installed systems may fall within physical damage coverage, but their full value might require documentation or an added equipment limit.
Does Class B insurance cover a pop-top roof?
A factory or professionally installed pop-top may be insurable as part of the conversion. Its value and installation should be reported so the carrier can confirm coverage.
Start A Quote