
Motorcycle insurance premiums don’t have to drain your wallet. At Leslie Kay’s, Inc., we’ve identified the most effective ways riders can lower their costs right now.
From safety features to bundling strategies, motorcycle insurance discounts in 2026 are more accessible than ever. This guide shows you exactly which discounts apply to your situation and how to stack them for maximum savings.
How Safety Features Cut Your Motorcycle Insurance Costs
Anti-Lock Braking Systems Lower Your Rate
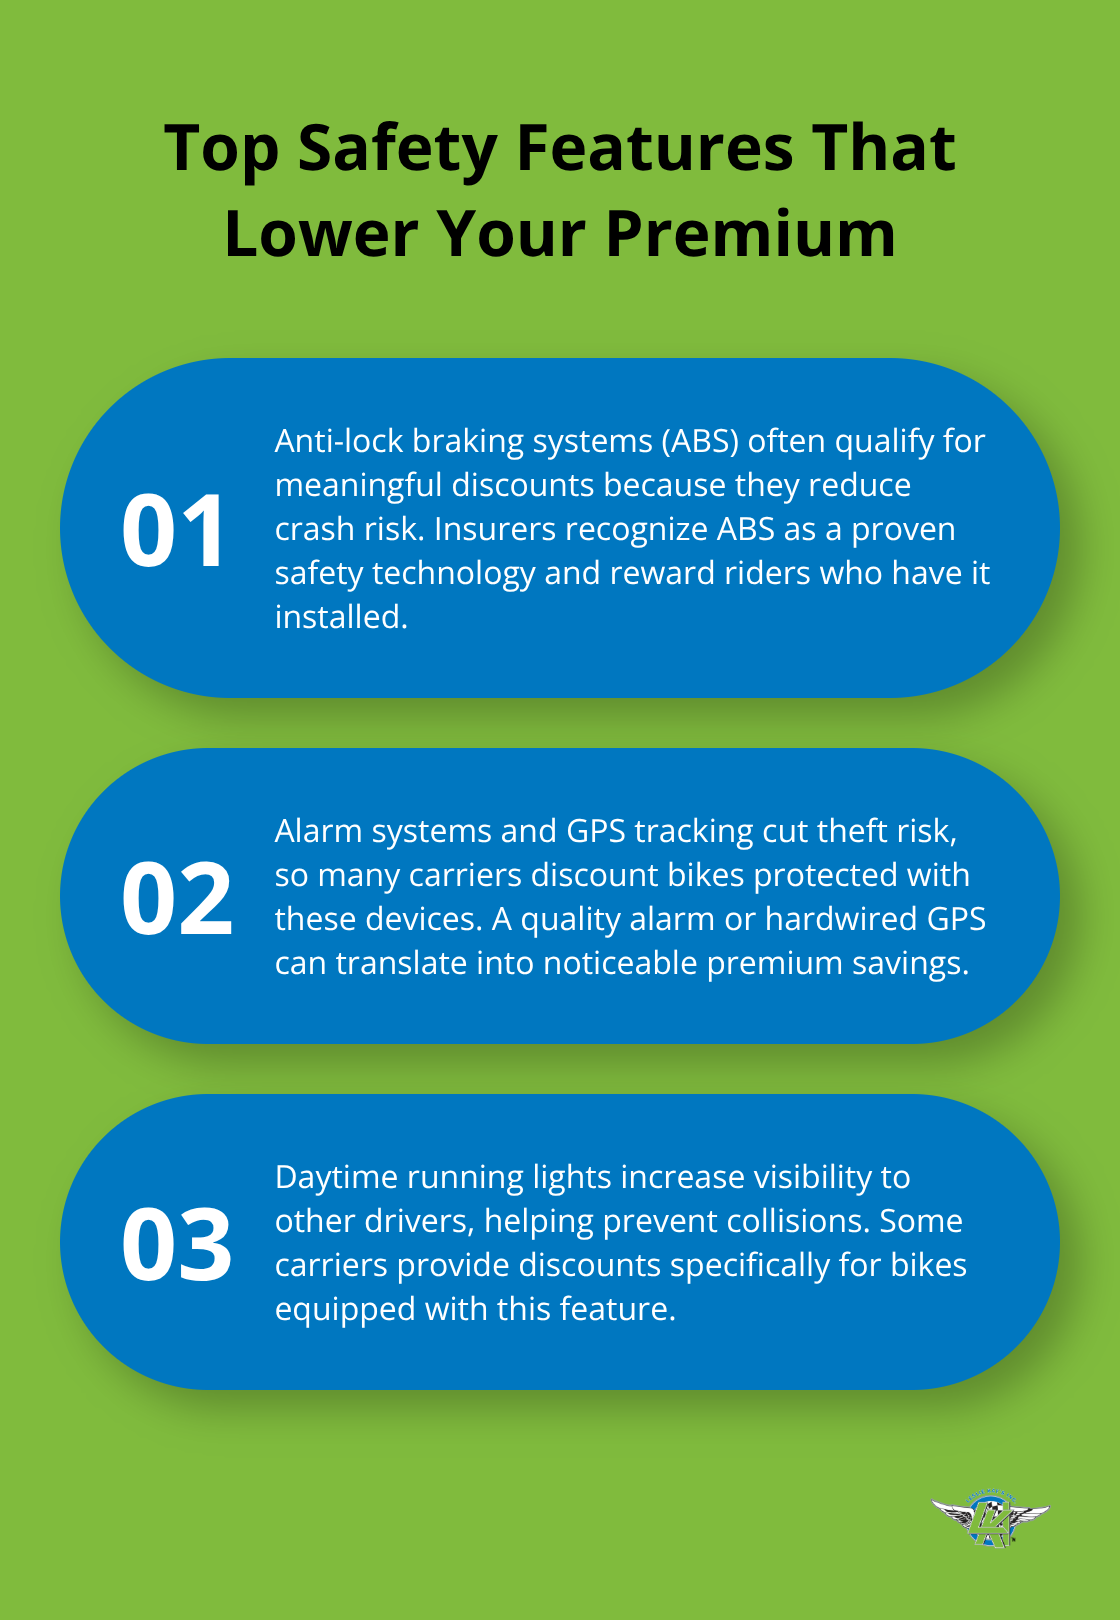
Safety features on your motorcycle directly impact what you pay for insurance. Motorcycles equipped with anti-lock braking systems (ABS) typically qualify for discounts between 5% and 15% depending on your insurer. The Insurance Institute for Highway Safety reports that ABS reduces motorcycle accident risk significantly, which is why insurers reward riders who have this technology.
If your bike has ABS, mention it when you get quotes, as some companies automatically apply this discount while others require you to specifically request it. The investment pays off immediately through lower premiums without any additional effort on your part.
Alarm Systems and GPS Tracking Cut Costs
Alarm systems and GPS tracking devices lower your premiums because they reduce theft risk. The National Insurance Crime Bureau found that motorcycle theft claims cost insurers substantial amounts annually, so insurers actively discount bikes with anti-theft protection. A hardwired GPS system or modern alarm system can earn you 5% to 10% in savings.
Older bikes can still qualify for these discounts if you add modern safety equipment yourself. The investment in a GPS tracker or upgraded alarm system often pays for itself within a year or two through premium reductions alone, plus you gain the genuine security benefit of protecting your motorcycle from theft.
Daytime Running Lights Qualify for Savings
Daytime running lights, while less common on motorcycles than other vehicles, qualify for discounts at certain carriers because they increase visibility. Some insurers offer 3% to 7% discounts for this safety feature alone. This simple addition makes your bike more noticeable to other drivers on the road.
Stacking Multiple Features for Maximum Savings
The real money comes from combining multiple safety features on your bike. A motorcycle with ABS, a quality alarm system, and daytime running lights could potentially stack these discounts to reduce your premium by 20% or more, depending on your insurer’s discount structure. However, not all insurers weight these features equally-some prioritize ABS heavily while others focus more on anti-theft measures.
When you contact an agent, provide a complete list of every safety feature your motorcycle has, including any aftermarket additions. Shopping your policy across multiple carriers matters because discount structures vary significantly. Your next step involves understanding how bundling your motorcycle coverage with other policies can unlock even greater savings.
How Bundling and Rider Behavior Lower Your Motorcycle Insurance Costs
Combine Your Motorcycle Coverage with Auto and Home Insurance
Combining your motorcycle policy with auto and home insurance at the same carrier typically saves you money on your total premiums. Most riders overlook this strategy because they assume their motorcycle coverage must stay separate-that assumption costs money. Most major insurers offer substantial multi-policy discounts that reward customers for consolidating their coverage. When you bundle, insurers view you as a more valuable customer with lower administrative costs, and they pass those savings directly to you. The discount applies immediately and requires no additional action beyond updating your policy information.
One practical tip: get quotes from your current auto insurer first, then compare those bundled rates against standalone motorcycle specialists. This comparison reveals whether bundling actually saves you money or whether a specialist carrier offers better rates for your specific situation.
Take Advantage of Low-Mileage Discounts
Seasonal riders benefit significantly from low-mileage discounts because some carriers offer them specifically for motorcycles. If you ride fewer than 2,500 miles annually, you qualify for discounts depending on your carrier. This discount recognizes that limited riding exposure reduces accident risk substantially. Document your actual mileage when you renew your policy because some insurers require proof through odometer readings or riding logs.
Your riding patterns directly impact your premium, so accurate mileage reporting works in your favor.
Complete a Safe Rider Course for Immediate Savings
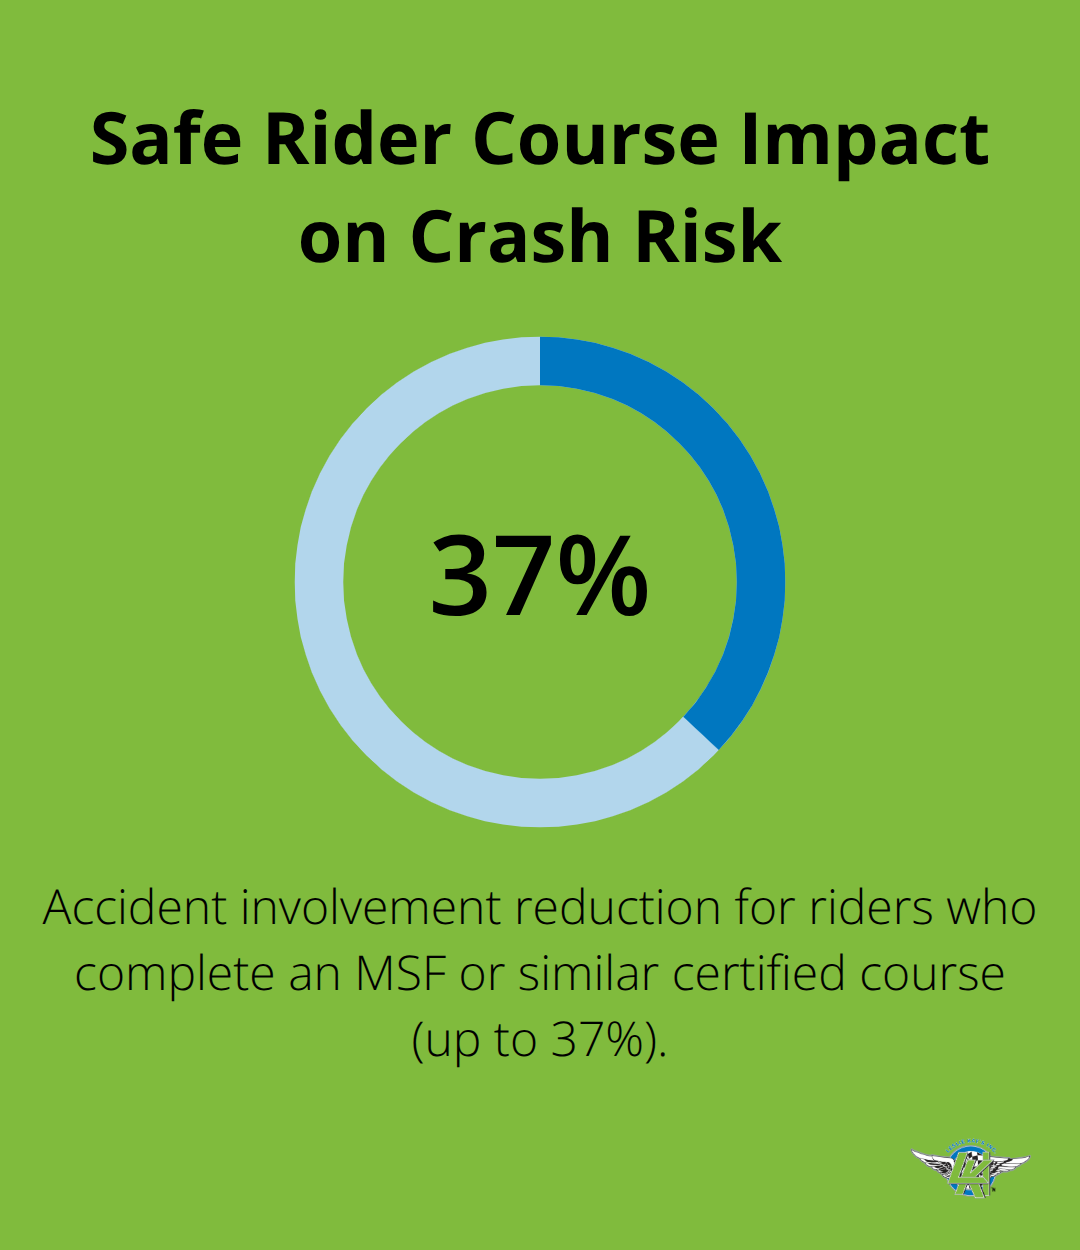
Safe rider courses deliver the most underutilized discount available in 2026. Completing a Motorcycle Safety Foundation course or similar certified training program qualifies you for premium reductions at most carriers, yet fewer than 20% of riders take advantage of this benefit. The Motorcycle Safety Foundation reports that riders who complete their courses reduce accident involvement by up to 37%, making this discount a genuine win for both you and your insurer.
Most courses cost between $150 and $300 and take just one or two days to complete, so the discount typically pays for the course within the first year alone. Some states offer additional incentives like waiving your riding test if you complete an approved safety course, which adds extra value beyond insurance savings. Contact your insurance agent before enrolling to confirm which courses your specific carrier recognizes for discounts, since not all programs qualify for all insurers.
Stack Multiple Discounts for Maximum Savings
Combining a safety course discount with bundling and low-mileage coverage creates a powerful triple discount that can reduce your annual premium compared to a basic standalone policy. The key involves understanding which discounts your specific carrier offers and how they interact with each other. Not all insurers weight these discounts equally-some prioritize safety training heavily while others focus more on bundling incentives. When you contact an agent, provide a complete list of every discount you qualify for, including your mileage patterns, completed safety courses, and other policies you carry. Shopping your policy across multiple carriers matters because discount structures vary significantly, and loyalty rewards programs offer additional opportunities to lower your costs even further.
How to Lock in Loyalty Discounts and Seasonal Savings
Multi-Year Policy Discounts Reward Your Loyalty
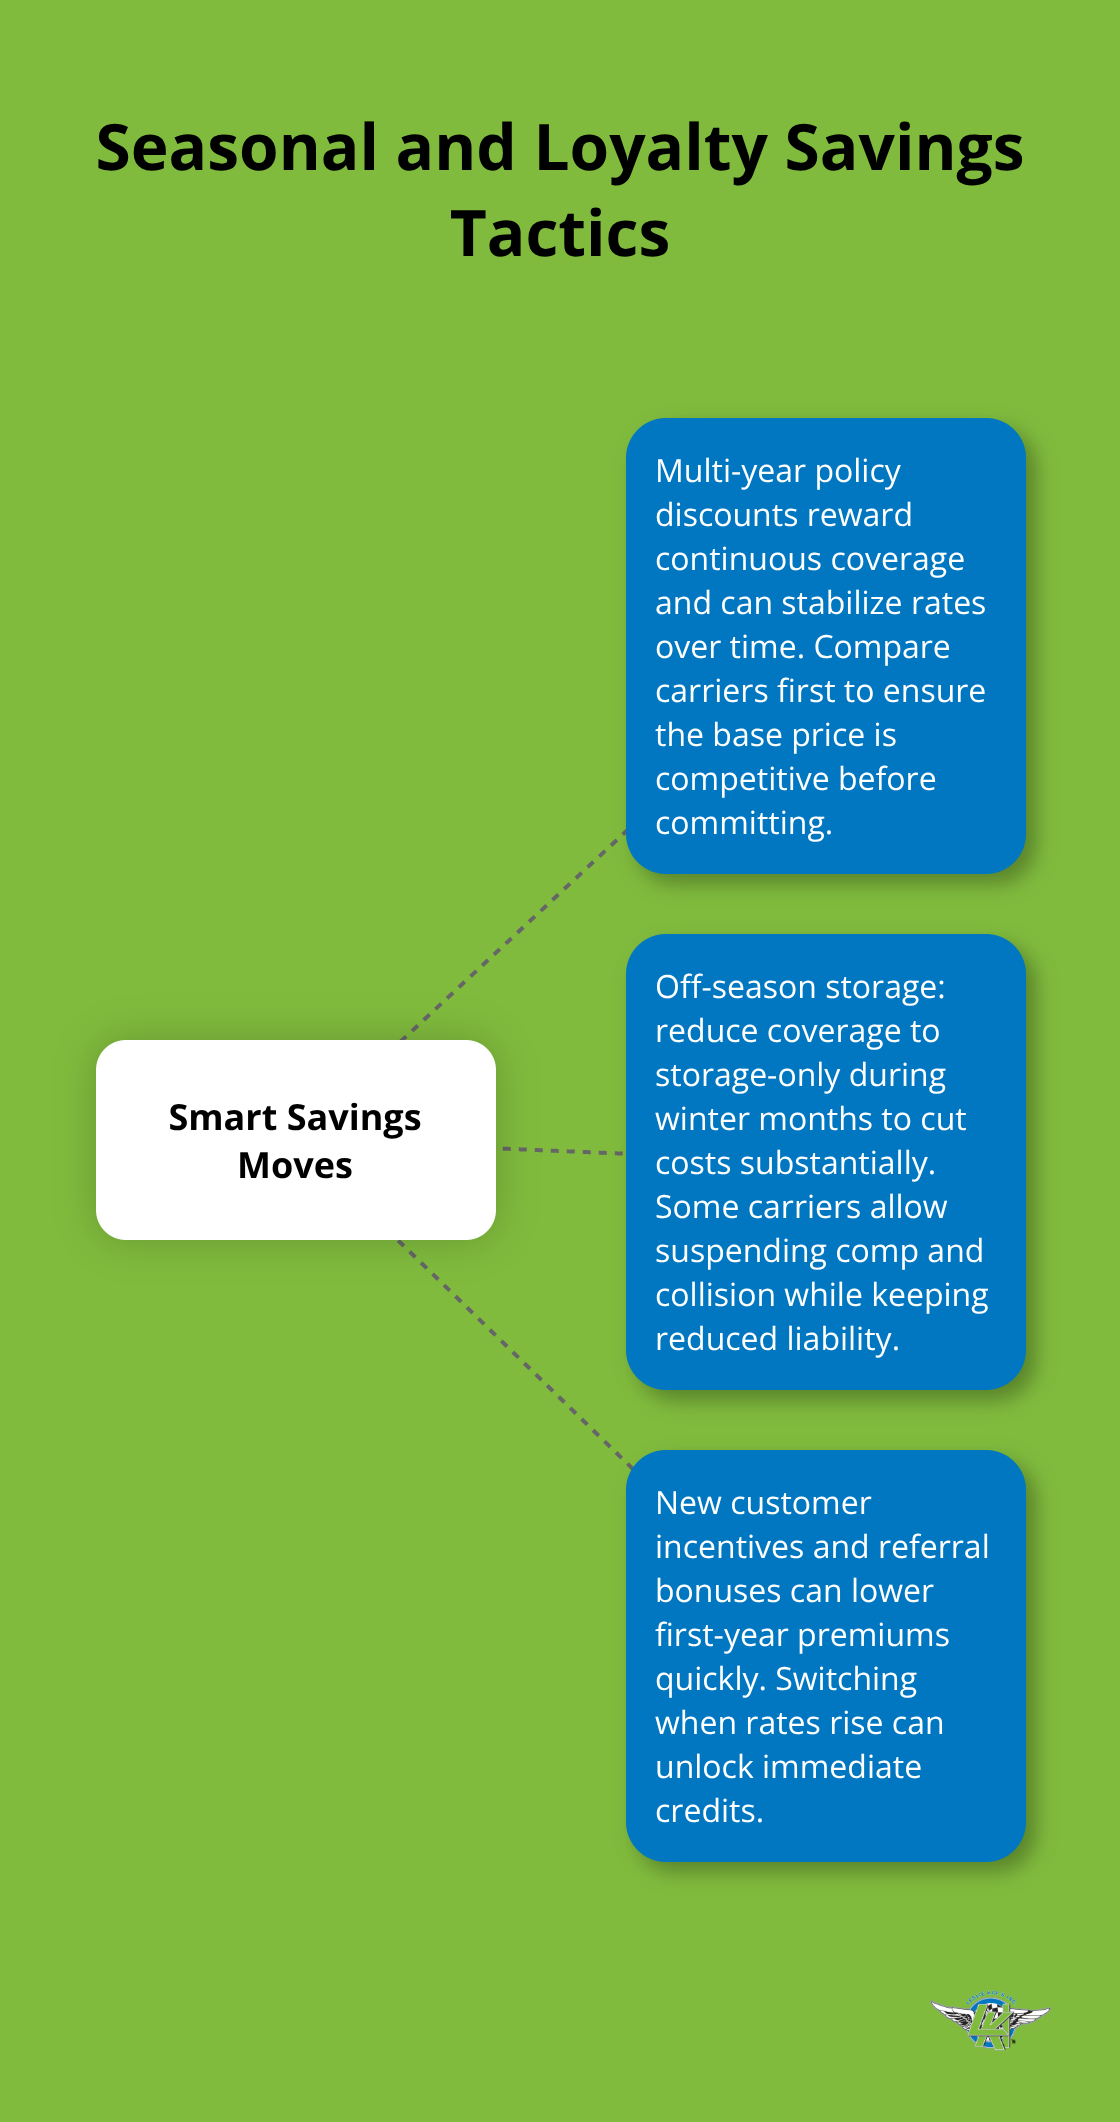
Staying with the same insurance carrier rewards your loyalty, and riders who switch companies every few years often leave thousands of dollars on the table without understanding what they sacrifice. Multi-year policy discounts typically range from 5% to 15% depending on your carrier, and some insurers offer additional rewards for maintaining continuous coverage without lapses. The longer you stay with a company, the more your rates stabilize and the easier it becomes to add discounts for new safety features or riding certifications.
However, loyalty discounts only work if your carrier is actually competitive on price to begin with. Before committing to a multi-year discount, compare your current rate against at least two other carriers to confirm you’re not locking yourself into an overpriced policy. Many riders discover they could save 20% to 30% by switching carriers, which far outweighs the loyalty discount they’d lose. The strategy that works best involves shopping every two to three years, even if you’re satisfied with your current coverage. This approach keeps your insurer honest on pricing while allowing you to capture loyalty discounts when rates are already competitive.
Off-Season Storage Discounts Cut Winter Costs
Off-season storage discounts apply specifically to seasonal riders who put their motorcycles away during winter months, and this discount gets underutilized because riders don’t realize their carriers offer it. If you store your bike for three or more consecutive months, you can typically reduce your coverage to storage-only policies that cost 40% to 60% less than full annual coverage. Some carriers allow you to suspend comprehensive and collision coverage while maintaining liability coverage at a reduced rate, which protects you legally without paying for theft or accident protection on a parked bike.
Document your storage dates and notify your insurer before you store your motorcycle so the discount applies immediately to your next billing cycle. This simple step can save you hundreds of dollars annually if you’re a seasonal rider who stores your bike for half the year.
New Customer Incentives and Referral Bonuses Accelerate Savings
New customer incentives and referral bonuses represent the fastest way to reduce your first-year premium if you’re switching carriers. Many insurers offer new customer discounts, and referring a friend can earn you account credits at some carriers. The combination of a new customer discount plus a referral bonus can reduce your initial premium substantially, making this an ideal time to switch if your current rates have crept upward.
Final Thoughts
You now understand the major discount categories available right now. Safety features like ABS, alarm systems, and daytime running lights reduce your premium directly. Bundling your motorcycle coverage with auto and home insurance at the same carrier typically saves money on your total costs, while low-mileage discounts reward seasonal riders and safe rider courses deliver the most underutilized savings available.
Maximizing your motorcycle insurance discounts 2026 requires action on multiple fronts. Document every safety feature on your motorcycle, complete a certified safety course if you haven’t already, compare bundled rates against standalone motorcycle specialists, and ask your current insurer about low-mileage discounts and off-season storage options that apply to your riding patterns. Shop your policy every two to three years to keep your rates competitive, even if you’re satisfied with your coverage.
The combination of multiple discounts stacked together creates substantial savings that most riders never capture. We at Leslie Kay’s, Inc. specialize in finding these overlapping discounts across multiple carriers to deliver customized policies that fit your budget and your riding lifestyle. Get a personalized quote to see exactly which motorcycle insurance discounts apply to your specific situation and start saving today.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.