
Motorcycle insurance doesn’t have to be complicated. At Leslie Kay’s, Inc., we know that finding rider friendly motorcycle quotes means getting coverage that actually matches how you ride, not settling for generic policies.
The difference between a good quote and a great one comes down to transparency, options, and support when you need it most. This guide walks you through exactly what to look for.
What Makes a Quote Actually Rider Friendly
Quotes That Match How You Actually Ride
A rider friendly quote reflects how you actually use your motorcycle, not how an insurance company assumes you ride. Most riders fall into distinct categories-commuters who log 5,000 miles yearly, weekend enthusiasts hitting 10,000 miles, or serious riders exceeding 15,000 miles annually. Standard quotes rarely account for these differences, which means you either overpay for coverage you don’t need or underpay and face gaps when claims happen.
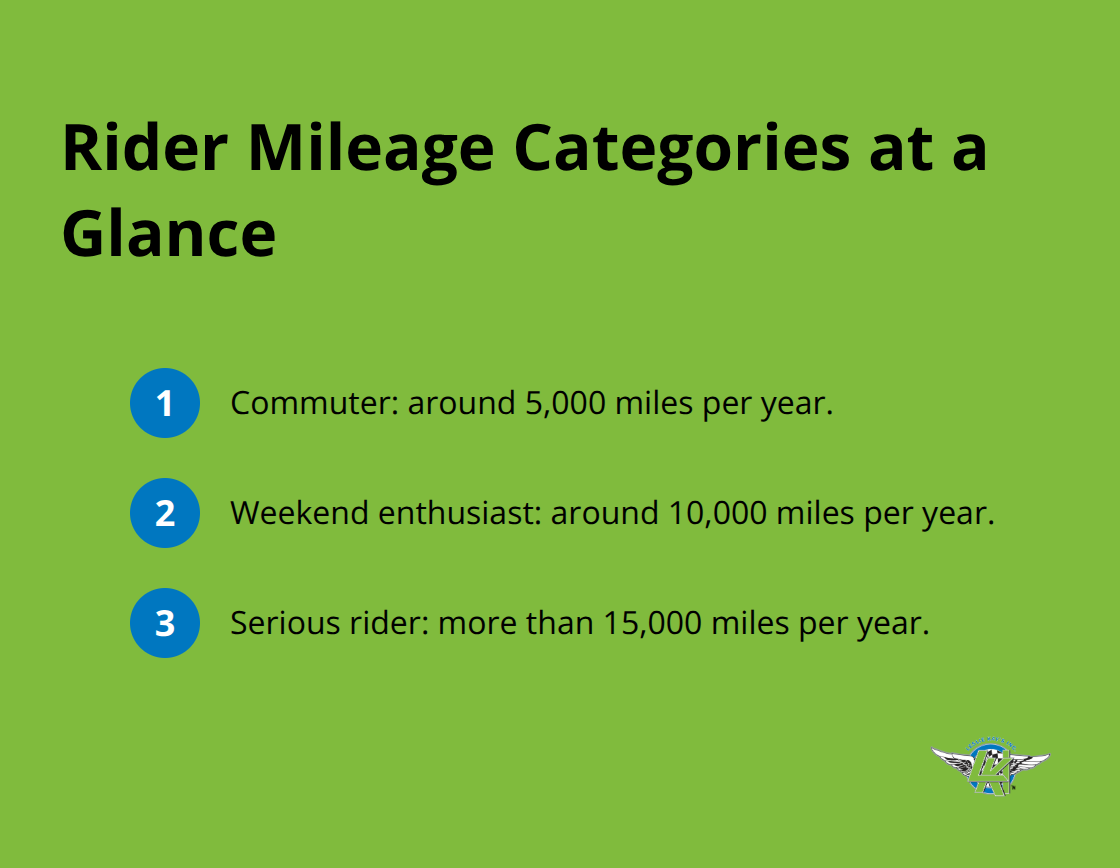
A truly rider friendly quote starts with carriers willing to customize based on your actual mileage, storage situation, and riding frequency. Some insurers charge identical premiums whether you ride three months a year or twelve, which punishes the casual rider. The best carriers adjust pricing based on whether you store your bike seasonally, ride it daily for work, or take it out on weekends only. This flexibility matters because a commuter facing rush hour traffic faces different risks than someone riding scenic routes on Saturday mornings.
Transparent Pricing That Makes Sense
Transparency in pricing separates rider friendly quotes from the rest. Hidden fees, unexplained rate increases, or surprise charges at renewal destroy trust fast. When you receive a quote, every component should be itemized-liability coverage costs, collision deductible impact, comprehensive add-ons, and any discounts applied.
Some carriers bury fees in fine print or quote a low rate that jumps significantly at renewal. The best quotes show exactly what you’re paying and why. You should see the breakdown without hunting through pages of documentation.
Speed Without Sacrificing Accuracy
The quote process itself should be straightforward. Most riders don’t want to spend hours on the phone or navigate confusing online forms. A quick quote process-ideally completed in under ten minutes-respects your time. Many carriers now offer instant online quotes with minimal information required, then allow you to add details later.
This speed doesn’t mean sacrificing accuracy. Carriers that specialize in motorcycle coverage understand that accurate quotes require asking the right questions upfront about your bike’s modifications, safety features, and storage location. The combination of fast processing and detailed customization creates a quote experience that actually works for riders, which sets the stage for comparing multiple options effectively.
How to Compare Motorcycle Insurance Quotes Effectively
Collect Quotes From Multiple Carriers
Most riders stop after collecting two or three quotes, which costs them money. The Insurance Information Institute reports that drivers who compare quotes from at least three carriers save money on premiums. Motorcycle riders benefit even more from shopping around because coverage options vary dramatically between insurers. One carrier might offer affordable theft protection while another specializes in custom parts coverage. Try collecting at least five quotes from different carriers to see the full range of what’s available.
Online comparison tools help, but direct quotes from insurers often reveal options that aggregators miss entirely. The time you invest here directly impacts your wallet for the next twelve months.
Look Past the Headline Price
Two quotes might both show liability coverage, but one includes uninsured motorist protection while the other doesn’t. Examine what’s actually included rather than focusing on the lowest number. Deductible options matter significantly-a lower premium with a higher deductible might work if you have emergency savings, but choosing minimum coverage to save $200 yearly creates financial disaster if you cause an accident.
Check whether each quote includes medical payments coverage, which pays your hospital bills regardless of fault. This protection separates adequate policies from incomplete ones.
Hunt for Discounts That Add Up
Ask each carrier about discounts you qualify for: safety course completion, bundling with auto insurance, multiple policy discounts, or paying your full premium upfront rather than monthly. These discounts often range from 10 to 25 percent and separate a good deal from an overpriced one. Many riders miss these opportunities simply because they don’t ask.
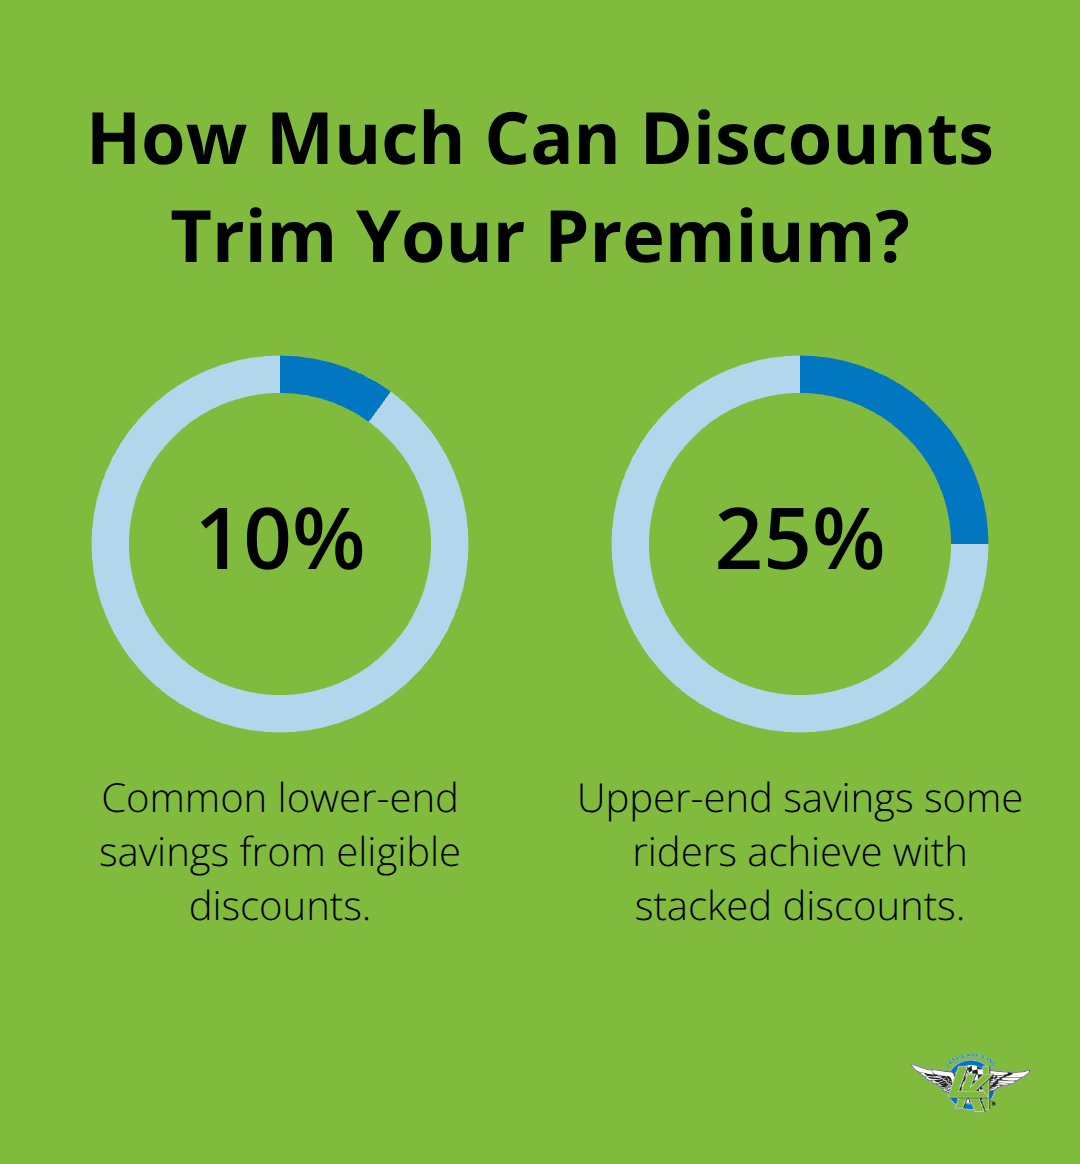
Some carriers offer discounts for specific safety features on your bike or for completing advanced riding courses. Others reward you for low annual mileage or for storing your motorcycle in a secure garage. The combination of these discounts (sometimes stacking multiple reductions) can substantially lower your final premium.
Evaluate Claims Support and Service Quality
Price alone shouldn’t determine your choice. A carrier offering the lowest quote might have poor claims support or slow response times when you need help most. Research how each company handles claims-do they offer 24/7 support, local adjusters, or online claim filing? Read reviews from actual riders about their experience filing claims, not just their experience getting quotes.
This evaluation sets the stage for understanding what separates a truly rider friendly carrier from one that simply offers cheap coverage. The next chapter explores the mistakes riders make when collecting quotes, which often stem from prioritizing price over these critical factors.
Common Mistakes Riders Make When Getting Motorcycle Quotes
Choosing Minimum Coverage to Save Money
Riders frequently sabotage their own quotes by prioritizing the lowest premium number over actual protection. Selecting minimum liability coverage to shave fifty or a hundred dollars off your annual premium creates catastrophic financial exposure. If you cause an accident injuring another rider or damaging property, your liability limits determine what you personally owe beyond insurance. Most states require minimum liability of 25/50/25, meaning $25,000 for bodily injury per person, $50,000 per accident, and $25,000 for property damage. A serious accident easily exceeds these limits, leaving you personally responsible for tens of thousands of dollars.
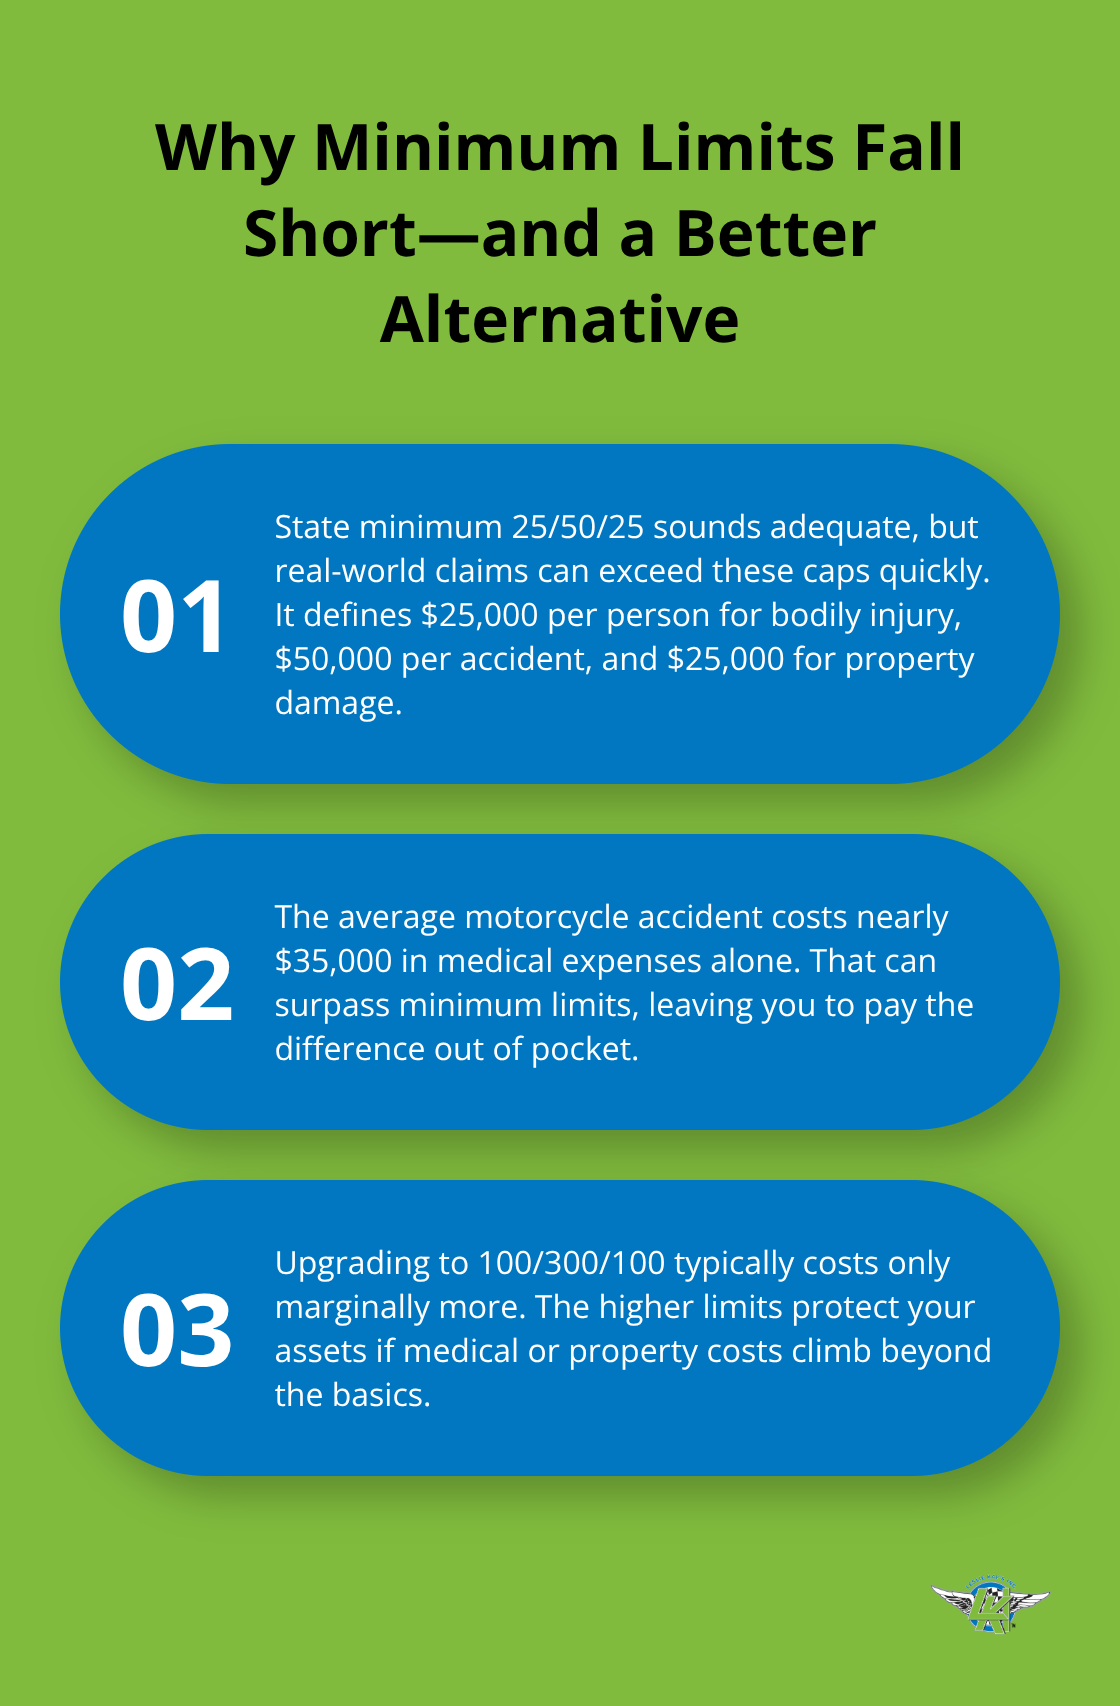
According to the National Highway Traffic Safety Administration, the average motorcycle accident costs nearly 35,000 dollars in medical expenses alone. Selecting higher liability limits of 100/300/100 costs only marginally more than state minimums but protects your personal assets if a claim exceeds coverage. The difference between inadequate and responsible coverage often amounts to just 100 to 200 dollars yearly, yet riders skip this protection constantly to chase the cheapest quote.
Not Mentioning Modifications or Custom Parts
Many riders fail to disclose motorcycle modifications or custom parts during the quote process. They believe aftermarket exhaust systems, engine upgrades, or custom paint jobs don’t matter, but insurers specifically exclude unmentioned modifications from coverage. If your motorcycle has 3,000 dollars in custom parts and you don’t list them on your policy, that investment receives zero protection in a theft or accident.
Some carriers offer custom parts coverage (adding 50 to 100 dollars annually) that covers exactly this scenario. Riders who skip this step face devastating losses when theft or collision strikes. The small premium increase for custom parts protection pays for itself the moment you file a claim involving those upgrades.
Ignoring Customer Service Quality
Riders overlook customer service quality when selecting quotes, focusing exclusively on price while ignoring claims support availability. A carrier offering a quote 20 percent cheaper means nothing if they lack 24/7 claims support, require you to ship your motorcycle across the state for repairs, or take weeks processing claims. Research actual rider reviews about claims experiences, not just quote experiences, through independent review sites and motorcycle forums.
The quote matters far less than what happens when you actually need your insurance. A carrier that answers your phone call at midnight on a Sunday or processes your claim within days rather than weeks proves its value when it counts most. Look for carriers that offer seven-day-a-week service and hands-on claims support (not automated systems) to handle your situation properly.
Final Thoughts
Rider friendly motorcycle quotes require you to invest time in comparison shopping rather than accepting the first low price you find. Collecting five quotes from different carriers, examining what each policy actually covers, and researching claims support quality puts you in control of your coverage decision. Most riders who skip these steps either overpay for unnecessary protection or face devastating gaps when accidents happen.
Your motorcycle modifications, annual mileage, and riding habits shape what coverage you actually need, so you must communicate these details honestly during the quote process. Resisting the temptation to select minimum coverage just to save a few dollars monthly protects your personal assets from catastrophic financial exposure. Asking about discounts you qualify for and understanding exactly what each policy includes separates confident riders from those who worry they made the wrong choice.
Start collecting quotes from multiple carriers this week and use the comparison framework from this guide to evaluate each option fairly. We at Leslie Kay’s, Inc. specialize in finding rider friendly motorcycle quotes by shopping multiple carriers to deliver customized policies with hands-on claims support and seven-day-a-week service. Visit Leslie Kay’s, Inc. to get started with quotes built specifically for how you ride, backed by a team that understands motorcycle coverage from personal experience.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.